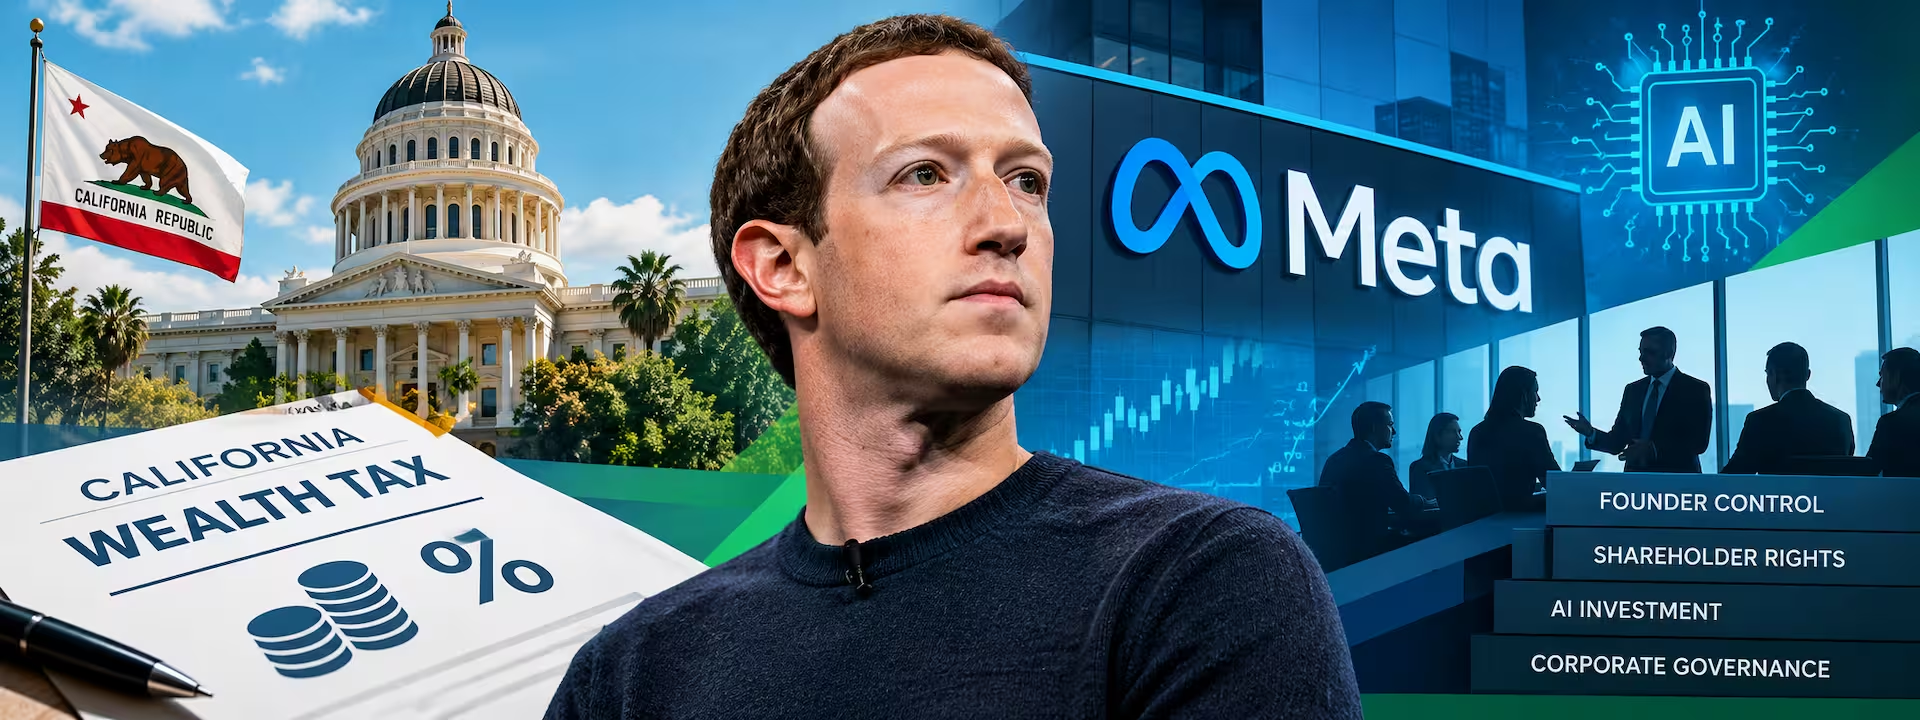
Zuckerberg’s California Tax Fight Reveals a Bigger Problem at Meta: Who Really Controls the Company?

Meta’s deal to keep Mark Zuckerberg in California exposes a deeper conflict between billionaire wealth, shareholder rights and the billions the company needs to compete in artificial intelligence.
Mark Zuckerberg’s reported concerns about California’s proposed billionaire wealth tax have led to an agreement that does more than address his potential personal tax bill. The arrangement also highlights a longstanding question surrounding Meta: how can the company raise money, fund its artificial intelligence ambitions and preserve its founder-led structure without creating a conflict with the interests of other shareholders?
According to an October 22 report by Reuters, Meta agreed to a structure involving new non-voting shares and an eight-year commitment for Zuckerberg to remain a California resident, subject to specified exceptions.
The deal follows months of negotiations between Zuckerberg and members of Meta’s board, according to a company filing detailed by The Washington Post.
The immediate issue was a proposed tax. The more consequential question, however, is what happens when the personal financial decisions of a founder are closely connected to the company’s voting structure, capital requirements and future strategy.
California’s Proposed Wealth Tax Put Zuckerberg’s Control at the Center of the Debate
California voters are expected to consider Proposition 40, a proposed one-time wealth tax targeting certain billionaires, in November 2026. As described in the coverage, the measure could impose a tax of up to 5% on qualifying covered assets valued above $1 billion if approved.
For Zuckerberg, whose fortune is largely tied to his Meta holdings, the potential liability could be substantial. But the challenge is not simply how much money he might owe.
Much of his influence at Meta comes from shares that carry greater voting power than ordinary stock. Selling those shares to raise cash could affect his ability to control important company decisions.
Forbes reported that the filing described concerns about Zuckerberg’s voting control potentially declining from approximately 60.6% to 53% if he had to sell substantial amounts of his supervoting shares. The actual outcome would depend on the applicable tax rules and the transactions involved.
This creates a distinction that is often lost in discussions about billionaire wealth: owning a large fortune is not the same as having readily available cash, and selling assets to generate that cash can have consequences beyond the transaction itself.
For Zuckerberg, those consequences extend to his influence over one of the world’s largest technology companies.
The Stock Deal Also Addresses Meta’s Need for AI Funding
The proposed tax is only one part of the story. Meta is also facing the enormous cost of building its artificial intelligence business.
According to The Washington Post’s account of the company’s regulatory filing, Meta’s board and management concluded that the company would need additional capital to support its AI ambitions. A new class of stock could provide funding for acquisitions, employee compensation and other corporate needs.
Meta’s planned arrangement involves creating non-voting Class C shares, with the company announcing a distribution structure intended to produce an effective two-for-one stock split in January 2027.
The structure matters because it separates economic ownership from voting rights. Investors can hold shares that carry economic value without receiving the same voting power attached to Meta’s existing voting stock.
Under the reported agreement, Zuckerberg will initially be able to sell a portion of the newly allocated shares, with additional shares becoming eligible for unrestricted sale over time while he continues in his full-time leadership role.
Forbes reported that the board committee estimated the arrangement could make approximately $20 billion accessible to Zuckerberg. That figure is not a guaranteed cash payment; the amount ultimately available would depend on the share price and the terms governing sales.
The arrangement therefore serves more than one purpose. It gives Zuckerberg a potential source of liquidity, provides Meta with a new financing instrument and helps preserve the founder-led structure that the company considers important to its strategy.
The tax dispute has brought these objectives together in a way that makes their competing interests harder to ignore.
The Bigger Conflict Is Between Founder Control and Shareholder Rights
The most revealing part of the negotiations may be the disagreement over whether Zuckerberg should be able to sell shares while retaining his existing voting influence.
According to The Washington Post, board members resisted a structure that would allow the CEO to reduce his economic stake without a corresponding reduction in his control. Their concern was that such an arrangement could be unfair to other shareholders.
That disagreement goes to the heart of Meta’s corporate governance.
In a conventional public company, shareholders generally expect their economic interests and voting rights to operate within an established framework. Meta’s founder-led structure is different because Zuckerberg’s supervoting shares give him influence that exceeds what his ordinary economic ownership alone might suggest.
Supporters of founder control argue that it allows leadership to pursue long-term strategies without being distracted by short-term market pressure. That argument carries particular weight in AI, where infrastructure investments can be expensive and their returns uncertain.
But the same structure raises a difficult question: how much independence can a board exercise when the person whose decisions it must scrutinize also has the power to determine the company’s direction?
The filing described negotiations that became tense enough for three directors overseeing the stock discussions to consider resigning if the disagreement could not be resolved.
The fact that the board ultimately reached an agreement does not eliminate the underlying governance question. It illustrates how difficult it can be to balance the authority of a powerful founder with directors’ obligations to the broader shareholder base.
Why Zuckerberg’s Residency Became a Corporate Issue
Zuckerberg’s possible departure from California added another dimension to the negotiations.
Meta’s board reportedly believed that keeping its CEO near the company’s California headquarters was important to its operations and leadership. The filing referenced difficulties the company experienced during the COVID-19 pandemic when Zuckerberg could not be physically present with management.
That concern helps explain why residency became part of a corporate agreement rather than remaining solely a personal decision.
For Meta, the issue is not just where its chief executive sleeps. It is whether the company believes its leadership model depends on Zuckerberg’s continued presence and participation.
That dependence creates a potential vulnerability. When a company places so much strategic authority in one individual, a personal dispute can become a business risk.
The agreement may reduce uncertainty over Zuckerberg’s location for the next eight years, subject to its stated exceptions. But it does not answer the larger question of how Meta would respond if its founder’s interests diverged more sharply from those of the company or its shareholders in the future.
Could the Deal Become a Model for Other Founder-Led Companies?
Meta’s arrangement may attract attention from other companies whose founders hold substantial voting power while maintaining significant economic stakes.
The underlying problem is not unique to billionaires facing wealth taxes. Founders at public companies can encounter similar tensions when they want to sell shares, raise capital or diversify their wealth without giving up strategic control.
A structure that separates economic ownership from voting rights can offer flexibility, but it can also intensify scrutiny of how corporate decisions are made and whose interests they serve.
Whether Meta’s agreement becomes a model elsewhere will depend on its implementation, its reception among shareholders and regulators, and how the company’s financing needs evolve.
There is also an important distinction between a company issuing shares to finance growth and a founder obtaining liquidity from newly issued shares. The two objectives can coexist, but the details determine who benefits, what risks are created and whether existing shareholders are treated fairly.
Meta’s planned share structure should therefore be judged on more than its ability to keep Zuckerberg in California. Its longer-term significance will depend on how effectively it supports investment without weakening accountability.
The Outcome: A Tax Dispute That Exposed Meta’s Dependence on Its Founder
Zuckerberg’s agreement with Meta’s board offers a potential solution to an immediate problem, but it also reveals the extent to which the company’s financial strategy and leadership structure are intertwined.
The proposed California tax created a possible need for liquidity. Meta’s AI ambitions created a need for capital. Zuckerberg’s desire to preserve voting power complicated the structure of any solution, while the board had to consider its responsibilities to other shareholders.
These pressures converged in a deal that addresses several objectives at once.
The most important question is no longer simply whether Zuckerberg will remain in California or how much he might have to pay if voters approve the proposed tax.
It is whether Meta can continue to fund its AI ambitions, preserve the founder-led model it believes gives it an advantage and maintain a credible balance between executive authority and shareholder interests.
For a company competing to shape the future of artificial intelligence, that balance could prove as important as the money it raises.
